Utilizing Two Protections on a Travel Delay
We talk frequently about travel protections offered by credit cards and annual travel insurance policies. We’ve shared stories about how our own claims have gone, and we even have trip delay and cancellation guides for some of our favorite bank cards. But sometimes, one policy’s coverage isn’t enough and you need to utilize two protections on a travel delay.
I actually had an interesting delay back in August, and recently completed the claims process. I took a somewhat unique approach by using two different types of coverage to help cover my expenses. Between the two, I was able to recover almost everything I spent. This delay also inspired me to share some tips to help you prepare for delays, from the initial booking to navigating the situation when things go wrong. I thought I’d break down what happened, how my two claims went, and an important warning about trip delay coverage.
The Booking
I was trying to return from the East Coast when weather got in the way. Flying home to Pacific Northwest, I booked a trip from Washington D.C. back home to Seattle on American Airlines (DCA-PHL-SEA). I used my Citi / AAdvantage Executive World Elite Mastercard which has some nice travel protections, although I always carry an annual travel policy as well.
But back to the booking, because things got interesting before I even got to the airport. I had originally booked the entire trip in economy and was hoping to get an upgrade with my status. As usual, I was monitoring the flights closely a couple of days before departure when I noticed I could actually book directly into first class for just 12,000 more American miles. I could also get slightly better timing on the first flight. The original flight was a bargain, so a few more miles seemed worth it to make this trip much more comfortable. It’s worth noting that American didn’t charge me again as a separate booking. Instead, it treated the transaction more like a flight change. I was a little worried about how this might affect my coverage as things played out, but I had proof of my original flight booking.
The Delay
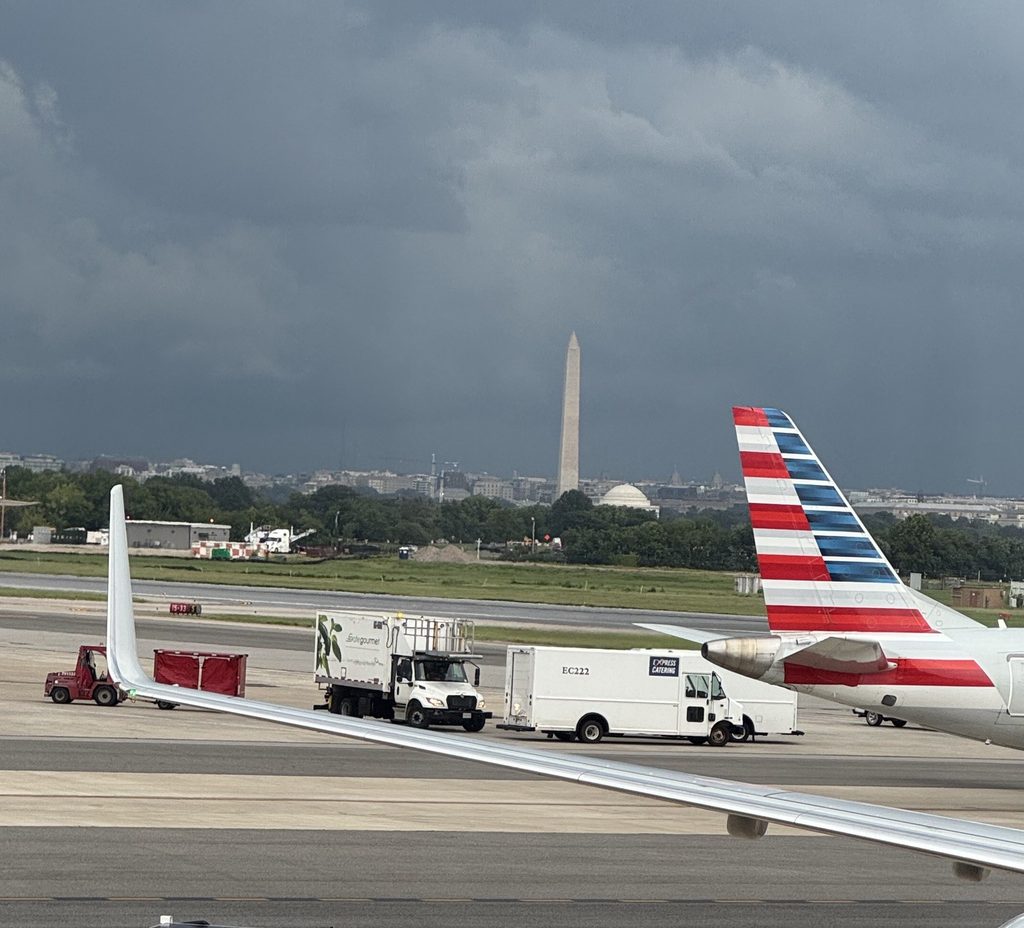
I wont dive into every detail, but here is a brief breakdown of what happened. My 1:55 PM flight out of DCA (Ronald Reagan Washington National Airport) was delayed, and we eventually boarded shortly after 4:00 PM. However, after boarding, severe weather on the East Coast caused a multi-airport ground stop. We were asked to deplane. Because of the delay, I was going to miss my connection in Philadelphia. AA staff in the lounge rebooked me on a later flight while keeping my original flight as a backup. Unfortunately, the delay lasted several hours, leaving me stranded overnight in Philadelphia.
The flight to Philadelphia ended up departing at 8:24 PM and AA was only able to rebook me on a flight roughly 24 hours later. That appeared to be the last available flight the following night, and I risked being stranded even longer if something else went wrong. Rather than wait, I rebooked myself on an Alaska Airlines flight early the next morning.
I used the tips and guidance from our flight delay strategies article throughout the delay, which definitely helped, even though delays are brutal no matter how prepared you are.
You’ll notice that one of those tips was having the lounge staff help with rebooking. This meant fewer people fighting to talk to an agent, which can make a big difference when everyone is trying to get rebooked at once.
My Expenses During Delay
Here is what I spent as a result of the delay:
- New Alaska Airlines Flight: $393.40
- Lyft Ride 1: $27.93
- Hyatt Select Philadelphia Airport: 199.80
- Uber Eats meal: $33.90
- Lyft Ride 2: $21.95
Total $676.98
It is worth noting, I put all charges on any card I wanted for the best protection or earning.
Claim One And The Warning
I started with my Allianz Annual Travel Policy which I pay $280 for. This is also where my biggest warning comes into play. Trip Delay always sounds great when you see a certain amount per day. I like having an annual policy because it covers a new flight booking which is why I rebooked myself to get home sooner. But it is the fine print of $200 per day, but per every 24 hours. So that rebooked flight of $383 would now only be covered for $200. That hotel I booked I thought might fall on day 1 and not day 2 now becomes not covered under Allianz and Trip delay. I did consider trying trip interruption to see if that would work, but the prompts on the claim are very specific. However this is where using the right card comes into play too.
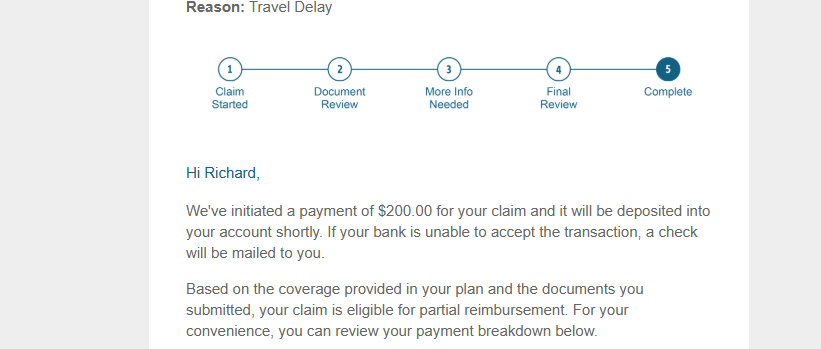
This process was pretty easy. I simply upload a synopsis of what happened and attached all of my documents. Those documents included screenshots of delays, any emails I received about the delay, and any receipts. I submitted it on August 31st and got my approval decision on September 18th.
Claim Two
That Citi / AAdvantage Executive World Elite Mastercard comes with $500 in coverage per day. So while it wont cover a new flight, I could claim everything else. That is exactly what I did. The process was almost as simple as the Allianz claim. I already had all of my documents from claim one saved and ready.
Due to my busy September I did wait until October, but I uploaded all of those via the Citi benefits link on October 9th. Often the companies will ask if you have other coverage or received anything so I did note that I received $200 towards the rebooked flight. I only claimed the rest of my expenses.
- Lyft Ride 1: $27.93
- Hyatt Select PHL Airport: 199.80
- Meal Uber Eats: $33.90
- Lyft Ride 2: $21.95
Total $283,58
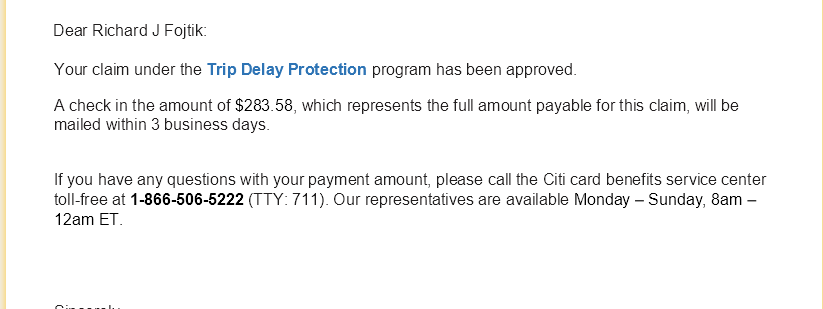
They requested more documentation on October 21st which was just showing I did fly back to Seattle. On November 4th my claim was approved for the requested amount. This meant my total loss between the two claims was only $193.40 out of the $676 spent. Considering how much the delay could have cost me, I was pretty happy with that outcome.
Utilizing Two Protections On A Travel Delay Claim: Top Thoughts
Having an annual travel insurance policy can be great, but pairing it with a credit card that offers travel protections can give you even more coverage when things go wrong.
The biggest lesson from my experience is to check those terms and conditions closely. Pay particular attention to how trip delays are defined, what expenses are covered, and how those maximum “daily” coverage limits are calculated. It’s also worth keeping your documentation organized. Having everything saved from my first claim made filing the second one much easier.
I certainly didn’t enjoy spending an unexpected night in Philadelphia or having to book another flight home, but being able to use two different protections helped me recover most of my expenses.
Have you used more than one protection Have a claim story to share? Come over to the Facebook group and let us know.