Bilt Collections Mistake
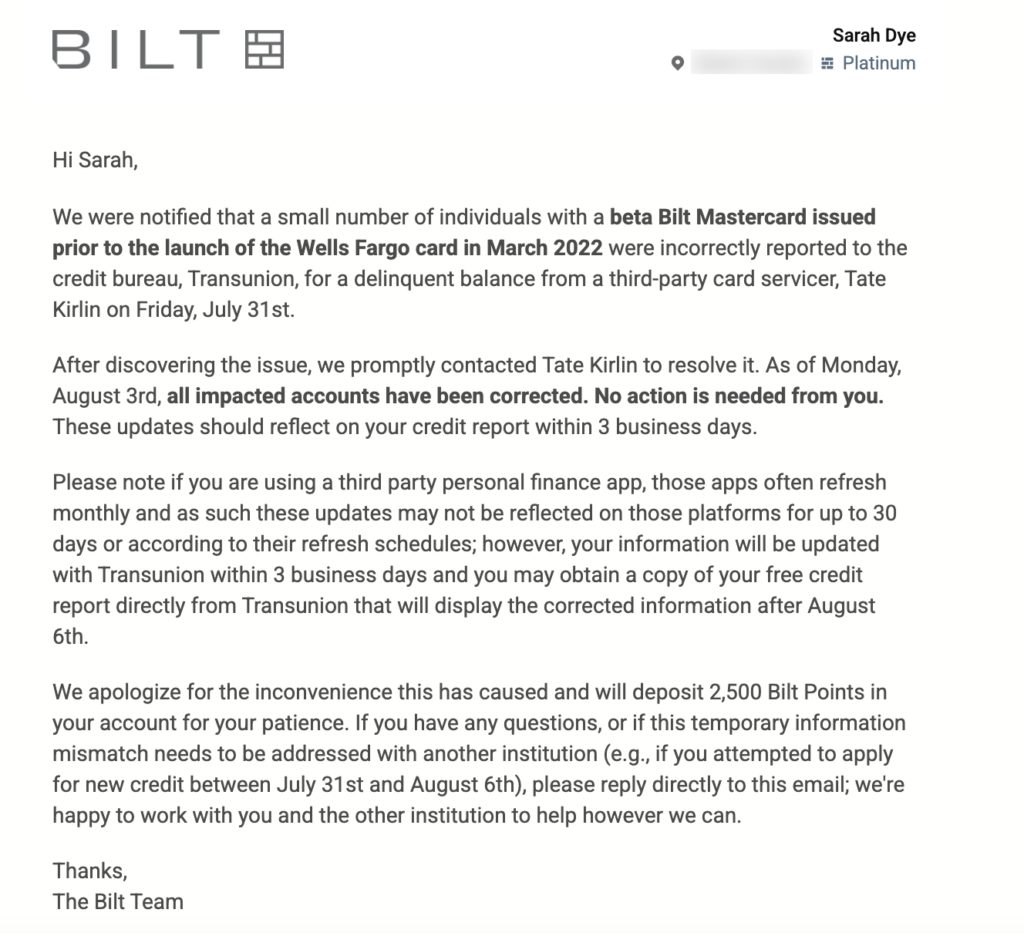
This is my personal Bilt collections mistake story. Before we get into the details, I want to start by saying that I have been an ardent supporter of Bilt since its initial launch. I got the “Beta” version of the card from a waitlist when it originally launched in 2021. Then, when the Bilt 1.0 card issued by Wells Fargo debuted in 2024, I applied for it. When Bilt 2.0 launched in January of this year, I applied yet again. This time for a Palladium card. We have covered Bilt extensively on this website and featured it prominently as a sponsor of our DFW meetup in 2023. So imagine my surprise when I received an alert from Credit Sesame (a free credit monitoring service) yesterday saying that I had an account reported in collections on my TransUnion credit report.UPDATE 8/3/26: Bilt emailed the affected customers indicating that the accounts have been corrected with the collection agency and that TransUnion credit reports should reflect this within 3 business days.
The Initial Alert
First, if you aren’t already monitoring your credit with one or more of the free services out there, I highly recommend setting that up right away. Credit Sesame and later Credit Karma both alerted me to this change on my credit report. If I had not received that alert, I may not have known for a while.
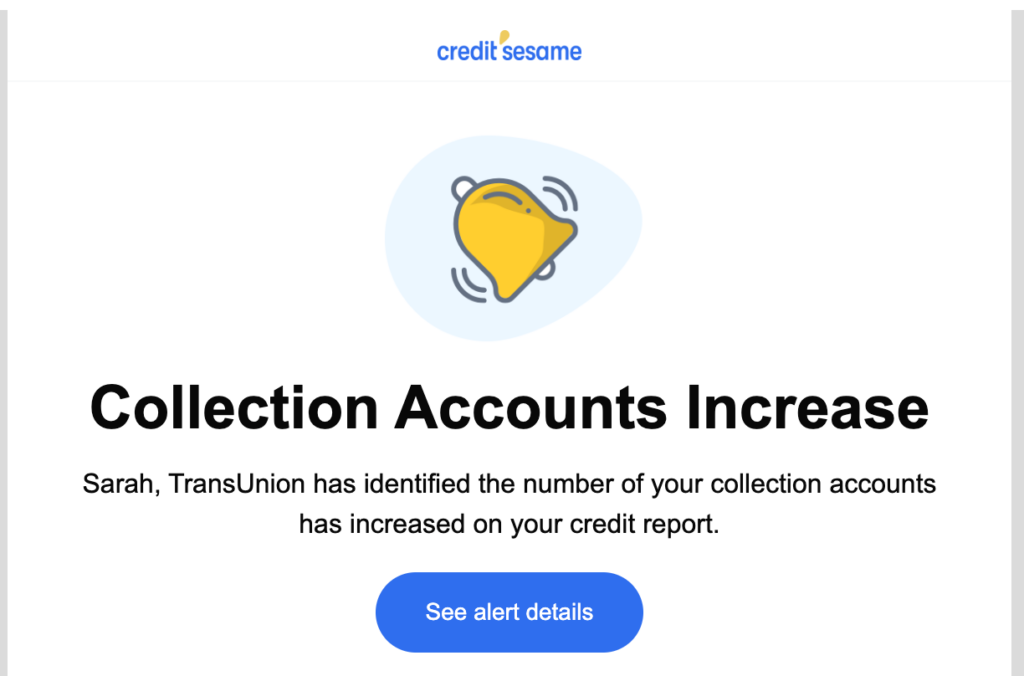
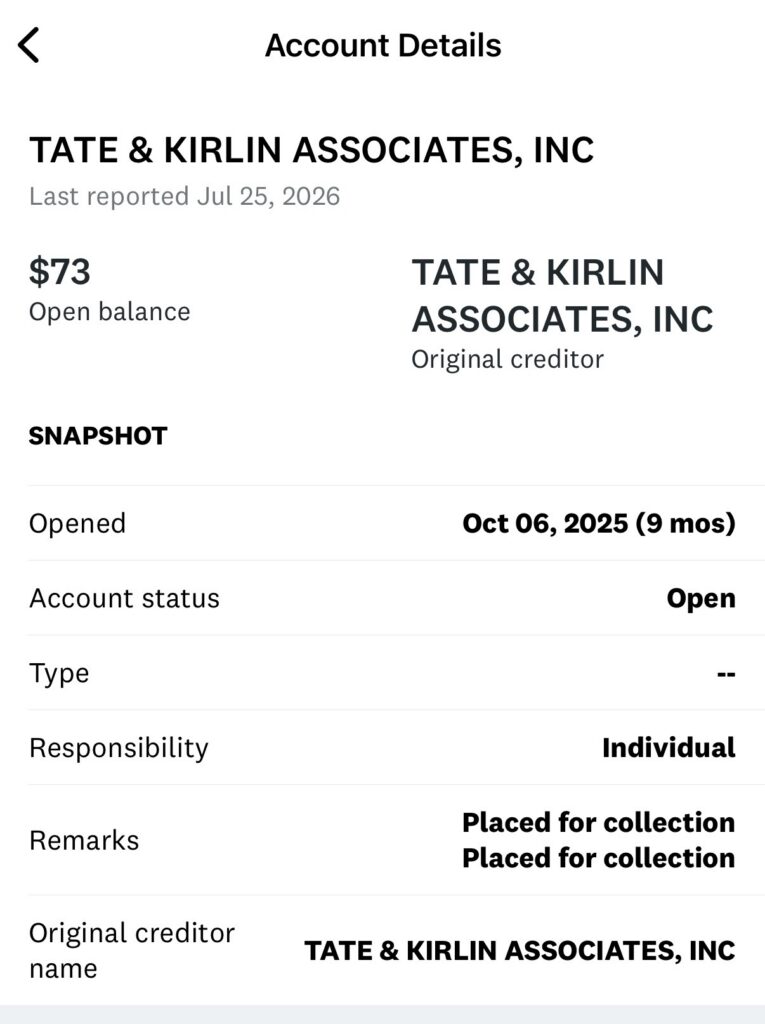
The alert came in, and I was completely shocked. We practice what we preach here at Travel on Point(s) about credit and credit cards: Pay everything in full, every month. A single missed payment has a huge impact on your credit score. When I looked at my report detail I saw the name “Tate & Kirlin,” the amount of $73 and a date of October 2025. Nothing about this rang any sort of a bell. How could I have an account in collections when I don’t have a single missed payment and have never received any communication about a bill? Surely, even if my meticulous record-keeping resulted in an oversight, there is absolutely zero chance I would jeopardize my credit over a mere $73.
Calling the Debt Collector
I called Tate & Kirlin right away. After a brief hold, an agent answered and asked for my “reference number.” Of course, I explained that I had no such thing, only this information from my credit report. Then she asked for my social security number, which I declined. Lastly, she asked for my name and searched for me that way. She found my records quickly, verifying both my address and my date of birth. She then said that it was a “consumer loan from Bilt.” I tried to keep my composure. This is impossible. Despite my requests, she insisted she had no further information. If I wanted more information, I needed to call Bilt. I asked for a phone number, and she said I should “Google it.”
Based on prior experiences calling Bilt, I decided to skip that step. And since I knew the date on the collections account was from before the transition to Cardless in January, I knew calling Cardless would be fruitless. So instead, I chatted with Bilt support in the app. And I fired off an email to Ankur Jain, Bilt’s CEO.
The Bilt Response
The Bilt support agent in chat told me to contact Cardless. I explained that the credit report information said it pre-dated the Cardless card. The agent then replied that they’d need more time to look into it and I’d get an email. That wasn’t particularly reassuring, but I knew my chances of an immediate resolution were low with this route.
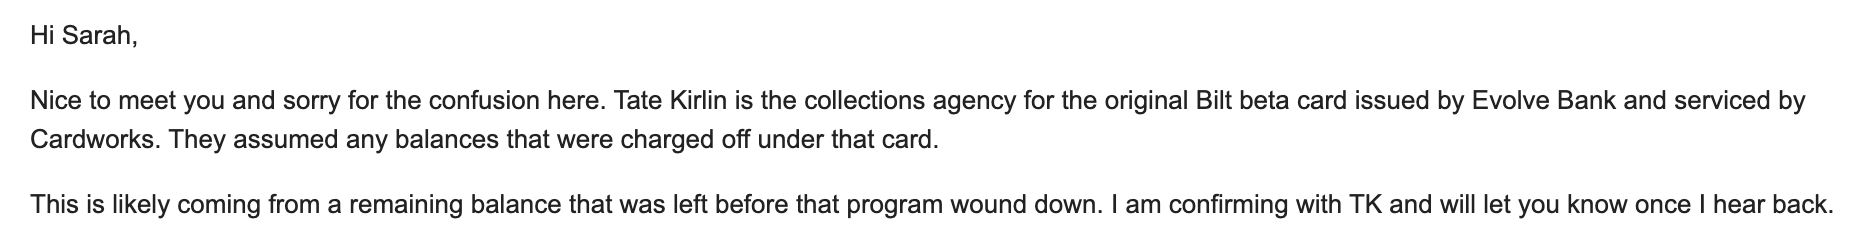
My email to Jain, however, got a lot more traction. He responded to my email within minutes and said he’d have his team look into it, CC’ing half a dozen other people within Bilt and Cardless. Shortly thereafter, a follow-up email came through from someone Jain copied on his reply. That response said it was “likely coming from a remaining balance that was left before that program wound down.” I knew I had no such balance.
Meanwhile, I started looking on Reddit. I couldn’t be the only person with this issue. Sure enough, there were other reports of the exact same thing. One now-deleted thread on Reddit that Google cached gave me a clue: The Redditor reported that the amount of the collections account on their credit report coincided with a fraudulent charge they disputed with Evolve Bank, the issuer of the Beta version of the Bilt card. Now it started to make sense.
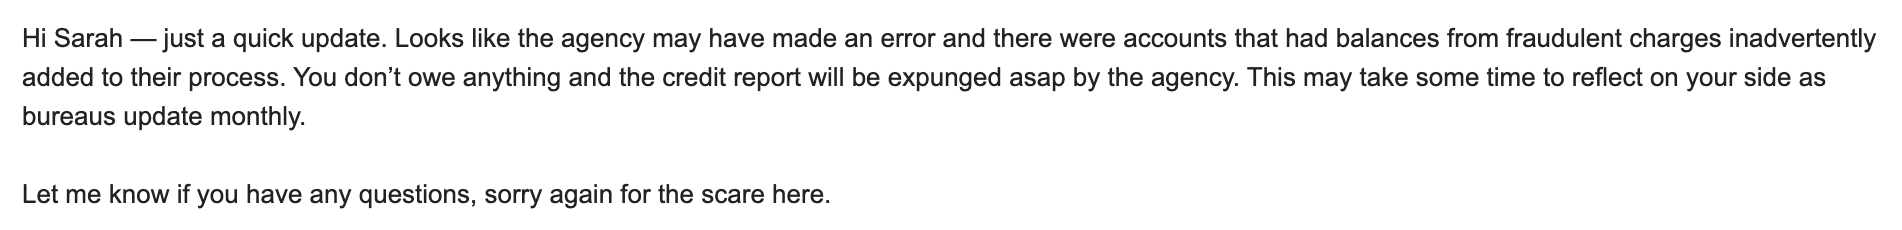
Through a series of subsesquent emails over the course of about two hours, Bilt confirmed this was the case. The ultimate resolution (for now) from the Bilt representative is: “You don’t owe anything and the credit report will be expunged asap by the agency. This may take some time to reflect on your side as bureaus update monthly.”
Update: August 3, 2026
Bilt emailed affected customers today indicating that the accounts have been corrected with Tate & Kirlin and credit reports should reflect this change within 3 business days. They are also offering a measly 2,500 Bilt points for my “patience” along with an apology for the “inconvenience this has caused.” While I appreciate the prompt attention to this matter, it is far more serious than $25 worth of Bilt points indicates. Also, as of the time of writing, I do not have these points in my account.
To Be Continued
While Bilt promises to resolve this in a way that removes the impact to my credit report, I’m still concerned. How did this happen? Are there legal implications? I cannot imagine what harm I would have suffered if this happened amidst a real estate transaction (or other credit decision) and I had to explain. I don’t want to apply for more credit right now while this resolution is pending, which throws a wrench into some of my plans.
Will Bilt offer additional compensation to those affected? How many customers are affected? I am curious to hear the answer to these questions.
Bilt Collections Mistake: ToP Thoughts
This is a colossal mistake on a lot of levels. While the prompt responses were reassuring, the story isn’t over. Hopefully the remedy is simple—remove the erroneous information from consumers’ reports – it raises lots of questions about the accuracy of credit reporting. Despite everything we’ve been through together, I’m still a fan of Bilt. I’d still recommend that you get the card if it works for you and you’re over 5/24. I still find the points valuable.
Do you have a Bilt collections mistake reporting to your credit, too? Come tell us what you think about this debacle over in our Facebook group.